By Tim Landy · October 3, 2026
“Should I wait for rates to drop?” is really a payment question. A lower rate later does not help if you cannot live with the payment today, and it does not help if the house you want is gone or more crowded when you come back.
Freddie Mac’s weekly survey put the average 30-year fixed at 7.28% for the week ending October 1, 2026. That is a national average for a strong borrower with 20% down. It is not your Austin quote. Your lender’s number is the one that belongs in the decision.
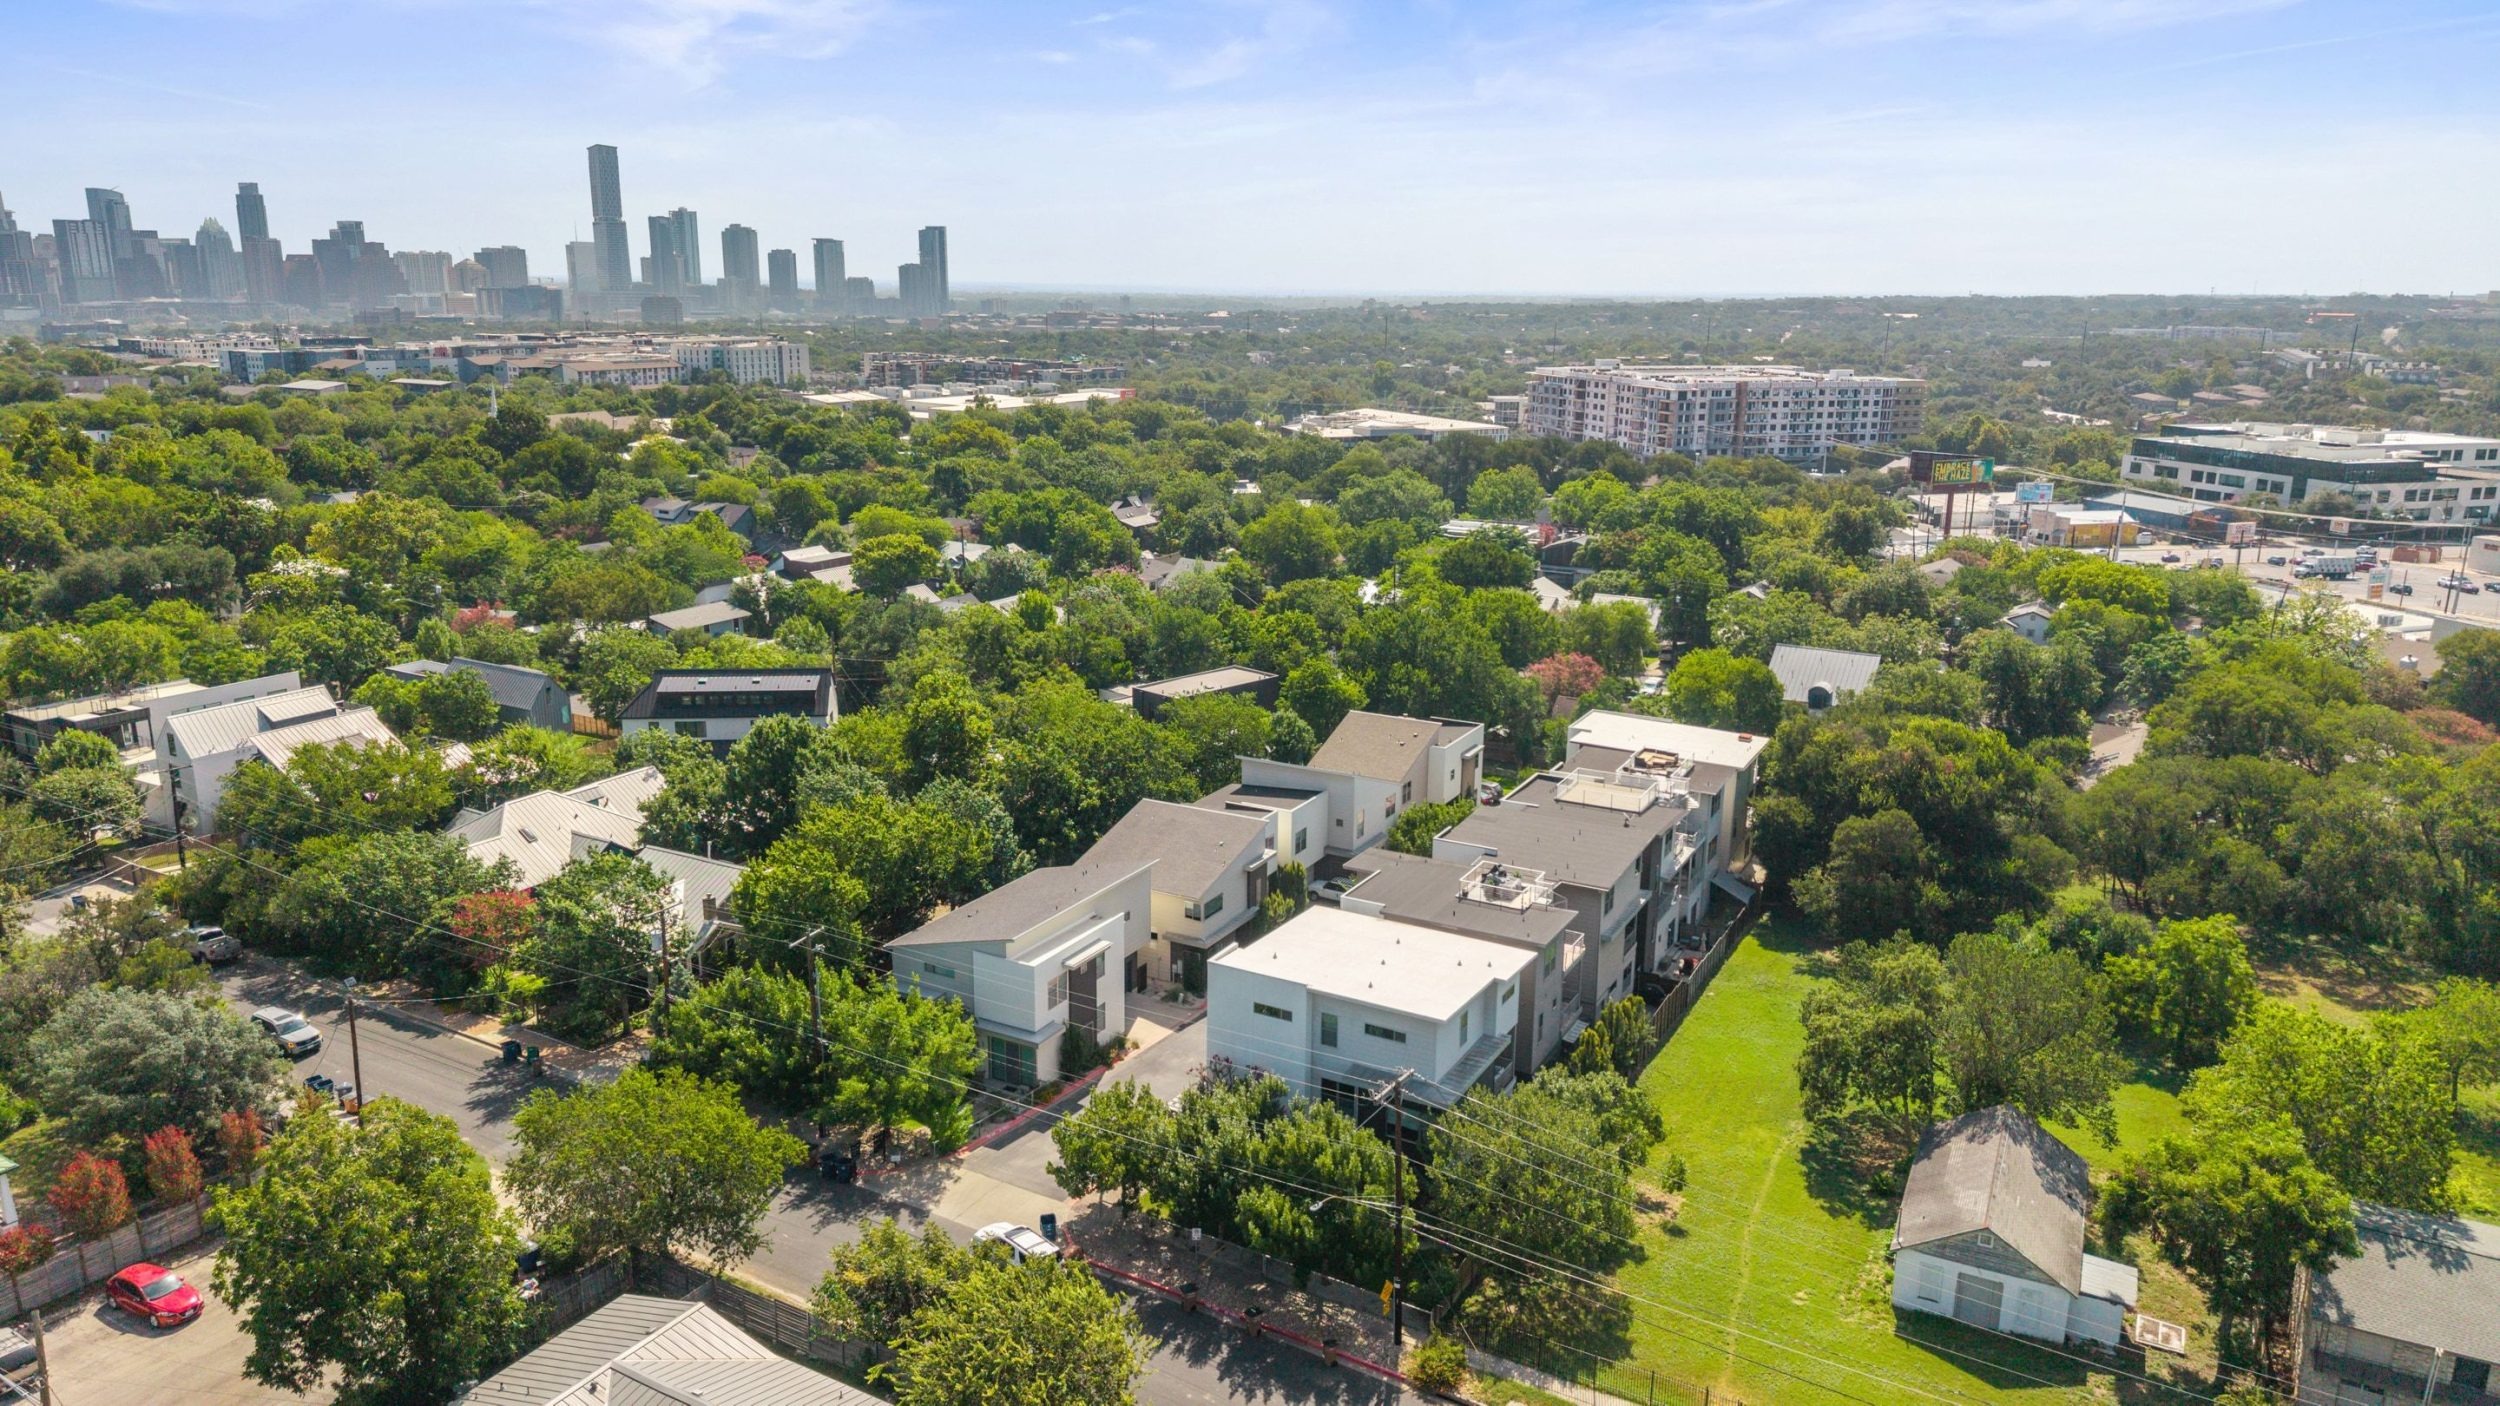
Austin is not one headline either. The October market update, from Unlock MLS data pulled October 3, shows an August metro median of $410,000, about 5.2 months of inventory, and about 60% of active listings with a price cut. Buyers have more choice than they did in a tight seller’s market. A higher rate still limits how many of them can use it. The label for that market is on Is Austin a buyer’s market in 2026? This post is only about timing.
“Good Time” Is a Payment Question, Not a Headline Question
The full payment has to work now: principal, interest, taxes, insurance, and HOA. A refinance later is a bonus, not the reason the house makes sense.
What You Give Up If You Wait
The house can sell. A later rate drop can bring back buyers who are sitting out, which can mean more competition, not a quieter market. Waiting has a cost even when the rate itself improves.
What You Give Up If You Buy Stretched
A payment that only works if rates fall, or if you move again in a year, is a bet. We would rather you pass on that house.
How Long You Need to Plan to Stay
Buying makes more sense when a move in the next year or two is unlikely. If the job, the school year, or the household might change soon, renting a bit longer can be the cleaner move. Our rent-versus-buy breakdown is here.
How to Use Today’s Inventory Without Betting on a Refinance
Extra choice is for finding the right house, not only for swinging at the biggest discount. Start with the first meeting before you tour. For how rates and prices interact, see what happens to home prices when mortgage rates rise.
A Simple Yes / Not Yet / Not This House Framework
- Yes: the payment works and you can see staying.
- Not yet: the payment is uncomfortable or the timeline is short.
- Not this house: the payment works, but this one fails the list you wrote down before you toured.
Frequently Asked Questions
Is it a good time to buy a house in Austin in 2026?
It is a good time if the full payment works at today’s rate and you can see staying. It is not a good time only because inventory is higher or because a headline says rates might fall. Read the current numbers on the Austin housing market update.
Should I wait for mortgage rates to fall before I buy?
Wait if today’s payment is uncomfortable or you may need to move again soon. Do not wait only for a better headline. A lower rate can also bring more buyers back into the same houses.
What if I buy now and rates drop later?
You may be able to refinance. Treat that as optional. The house still has to make sense at the rate you lock.
How long should I plan to own before buying makes sense?
Long enough that a move in the next year or two is unlikely. There is no magic number of years that fits every buyer. If the next chapter is already on the calendar, say so before you write an offer.
Does more inventory mean I should offer far under asking?
No. More choice means you can be selective. It does not mean every house is overpriced by the same amount. Price from the comps for that house, not from the metro headline.
What should I have ready before the first tour?
A real budget after taxes and insurance, a short list of must-haves, and a clear walk-away. That is the plan before you tour. Pre-approval belongs in that same first step, on the buyers page.
Want to run your own numbers at today’s rate? Talk with our team or call / text 512-693-8578.